Legal Spend Best Practices for Accruals and Budget Tracking
Invoice-only reporting tells legal leaders what the department already spent, not what it is about to spend. Accurate legal accruals paired with living matter budgets close that gap, turning a backward-looking record into a forward view of legal spend. Litify supports that shift by connecting matter data, billing, and spend reporting, so budgets, actuals, and estimates draw from the same source.
Legal departments are taking on more work than ever while also facing slimmer budgets. CLOC's 2026 State of the Industry Report found that time spent on regulatory compliance and cybersecurity has increased for 63% and 58% of departments, respectively, while 37% expect outside counsel spend to increase, down sharply from 58% the year before.
That puts financial discipline at the center of legal operations. Accurate legal accruals, combined with disciplined matter budgets and real-time insight into current matters, can help departments gain control of their budgets.
Read on to better understand the legal accruals tracking process, important metrics to measure, legal technology that can help, and where to start.
Why legal accruals and budget tracking belong in the same process
Accruals capture what has been spent but not yet billed. Budgets capture what a matter is expected to cost in total. Together, they provide valuable insight into the department's financial standing.
What legal accruals are
A legal accrual is the value of legal services already performed but not yet invoiced during the reporting period. Outside counsel works in one month and bills in the next, sometimes the one after. Accrual accounting closes that gap so the expense lands in the period the work happened.
Pay attention to these four terms that get used interchangeably but should be differentiated:
- Accrued spend: Work performed but not yet invoiced.
- Invoiced spend: Work billed for, whether or not it has been paid.
- Paid spend: Invoices actually disbursed.
- Forecast spend: Cost that is still expected before the matter closes.
Accruals matter most at monthly, quarterly, and year-end close, and they cluster around predictable triggers: active litigation, regulatory matters, transactions, and internal investigations.
The spend picture legal leaders actually need
Invoice-only reporting can show a budget that is not really available. A matter may look 40% consumed because only 40% has been billed, while three weeks of unbilled deposition prep wait in a firm's system for the end-of-the-month report.
A complete view of legal spend combines six elements:
- Approved budget
- Invoiced actuals
- Current accruals
- Forecast to complete, meaning the cost is still expected before closure
- Remaining budget
- Flagged variance when the numbers exceed a predetermined threshold
Accrual accuracy makes the rest of the reporting credible, since forecasts inherit the quality of the estimates underneath them. When Legal and Finance work from one set of numbers, period-end adjustments shrink. Strong legal spend reporting depends on that shared foundation.
Where legal accrual and budget processes break down
Most legal spend problems are process problems, not people problems. Six patterns account for the majority of issues a department may face:
- Accruals collected via email and spreadsheet: Version control breaks down, responses go missing, and formats vary by firm and department, with no audit trail.
- Estimates arrive too late to be useful: Without a standard cutoff, firms reconstruct activity after the fact, and the legal operations team is tasked with chasing down the information.
- Matter budgets go stale after approval: Scope changes, new phases, and funding requests live in email threads rather than in the budget itself, so the approved figure and the actual expectation differ.
- Finance, billing, and matter data disagree: Different matter identifiers and vendor names force manual reconciliation every month.
- Overruns are measured after they happen: With no variance thresholds and no forecast to complete, executive conversations explain history rather than manage future cost.
- Some vendors never submit LEDES files: Local counsel, experts, and specialty vendors often bill in PDF or paper form, leaving part of legal expense tracking outside the system that governs everything else.
Build a repeatable monthly accrual process
Accruals management improves when the process is no longer a monthly scramble. Three habits do most of the work.
Set one accrual calendar and stick to it
A published calendar removes the negotiation from every cycle. Create one with these five fixed points:
- Request date: When requests go out to firms.
- Firm submission deadline: The hard cutoff for estimates.
- Internal review window: Time for legal operations to question submissions.
- Finance cutoff: When numbers lock for close.
- True-up timing: When estimates are compared against actual invoices.
Add an escalation path for firms that miss the deadline, plus extra review time at quarter-end and year-end. The same calendar every month reduces one-off requests to almost none.
Standardize what outside counsel submits
Require the same fields from every firm, every cycle: matter ID, reporting period, unbilled fees, unbilled expenses, work performed through the cutoff, material work expected before period-end, and the assumptions behind the estimate.
Financial expectations belong in your outside counsel guidelines alongside billing and staffing requirements. CLOC publishes a template teams can adapt, covering accrual deadlines, budget refresh frequency, advance notice before an overrun, and escalation contacts. Firms manage to the standards you write down, which is why outside counsel spend conversations go better when expectations are set in advance.
Review by exception, then true up
Nobody has time to examine every accrual. Set materiality thresholds with Finance so attention goes where the dollars are, then flag the exceptions:
- Missing accruals on active matters
- Month-over-month movement
- Deviation from a firm's historical run rate
- Matters approaching their approved budget
- Scope changes with no corresponding budget revision
After invoices arrive, compare each accrual to what was billed. Separate timing differences from estimation problems, then feed the findings back into firm conversations. The corporate Finance team sets accrual policy and documentation standards, and legal accrual accounting should follow them rather than run in parallel.
Track matter budgets so problems surface before the overrun
Legal budget management works when the budget is a living document rather than an approval artifact. That takes structure, a broader tracking equation, and agreed triggers.
Budget at the matter level, with a named owner
Matter-level budgets should capture expected total cost, fees separated from expenses, a phase breakdown where the matter type supports it, and firm, rate, and duration assumptions. Fee overruns and expense overruns have different causes and fixes, so they should be kept separate.
Every budget needs one owner accountable for keeping it up to date, since shared ownership can lead to no one owning it. Housing budgets inside the existing matter management software keeps the owner on the same record as everyone else.
Track more than budget versus paid invoices
Start with an approved budget, subtract the invoiced spend, subtract the current accrual, then compare what remains against the forecast to complete. When the forecast to complete exceeds the remaining budget, the overrun becomes visible before the invoice arrives.
Also track the percentage of the budget consumed, the variance amount, and the variance percentage. Budget tracking gets easier when those three numbers are calculated consistently for every matter and every firm on the panel.
Define the triggers that force a budget conversation
Set consumption thresholds at 50%, 75%, and 90%, tuned to matter size and risk. A 90% threshold on a routine employment matter and a 50% threshold on a high-exposure case are both defensible.
Event triggers are crucial, and should include:
- Scope expansion
- A new jurisdiction or an added party
- A litigation phase change
- Material staffing or rate changes
- Forecast variance beyond tolerance
When a trigger fires, re-forecast rather than raise the number. Record what changed, the new expected total, the rationale, and the original baseline, which is what makes post-matter analysis possible.
Measure whether your legal spend process is improving
Legal spend analytics should inform strategic decisions, not serve as vanity metrics shared quickly during a meeting.
Start with these core components:
Questions your legal spend analytics should answer
- Which matters are forecast to exceed budget?
- Where is spend growing fastest: by firm, business unit, matter type, or jurisdiction?
- Which matters have no current forecast attached?
- Are budget changes driven by real scope shifts or by weak initial estimates?
Most departments skip #4, and it is the question that reveals whether the problem is the matters or the estimating.
Four metrics worth tracking
- Accrual accuracy: Estimate versus eventual invoice, in dollars and percentage, by firm and by matter.
- On-time submission rate: Percentage of accruals received before the cutoff, so any repeat patterns can be identified and addressed.
- Budget variance: Actual plus accrued spend against approved budget, and forecast total against approved budget.
- Forecast accuracy: Prior forecast against final matter cost, segmented by matter type.
Include financial management in outside counsel performance reviews
Accrual accuracy, submission timeliness, forecast reliability, and billing guideline compliance belong in your outside counsel reviews alongside service, outcomes, and responsiveness.
Use these insights to improve estimates together, since scoring firms solely on variance doesn’t capture the full picture and may incentivize the wrong thing. Tracking these alongside your other legal KPIs keeps the review balanced.
How legal spend management software makes the process more reliable
While structured process discipline takes a legal department a long way, it inevitably hits a ceiling when scaling.
Signs the spreadsheet has reached its limit
Watch for high matter volume, a large outside counsel panel, multiple business units or geographies, an identical monthly collection cycle, recurring reconciliation problems, and increasing reporting demands from Finance.
The ACC Legal Operations Maturity Model describes the early stage of maturity as still having budgets tracked in spreadsheets, if at all. Two or three of those early-maturity signals together usually mean that manual processes likely constrain the team.
What to look for in a legal spend management platform
A legal spend management system should cover:
- Billing and invoice review
- Matter-level budgeting and accrual capture
- Budget-to-actual reporting and spend analytics
- Phased matter budgeting, driven by timeline and by milestone
- AI support for invoice review and rate analysis
- Configurable approval and escalation workflows
- Finance and ERP integration
- Permission and audit controls
- Financial data held at the matter level
Throughout the workflow, automation should handle collection, reminders, and routing so people can focus on addressing exceptions.
Connect matter data and spend data in one platform
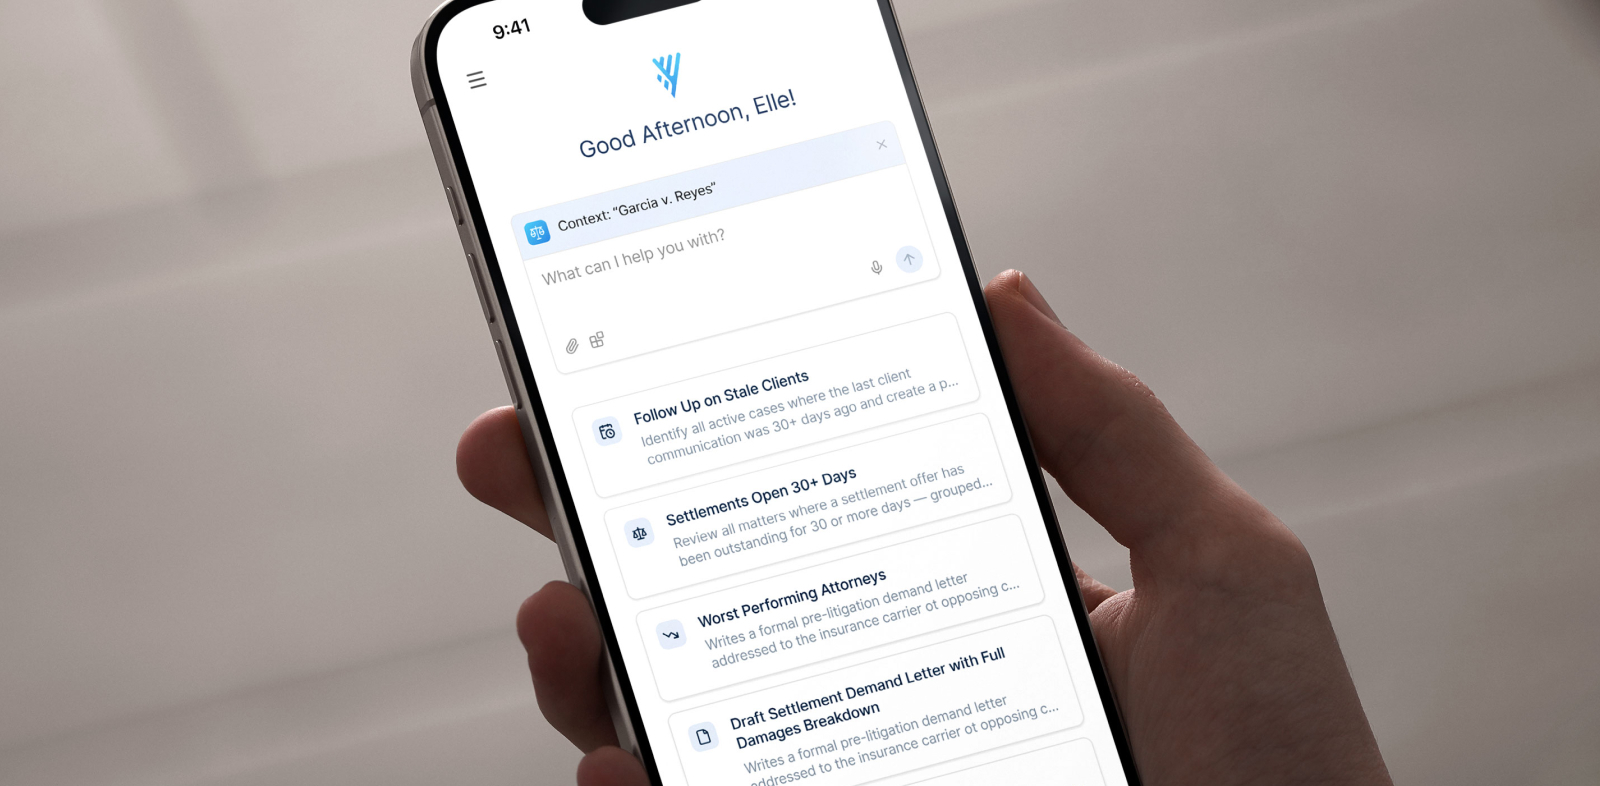
Litify leverages the power of the Salesforce platform to bring matter management, billing, reporting, and spend visibility into a single enterprise legal management software environment.
Matter information supplies context. Billing supplies the actuals through modernizing legal eBilling workflows. Budgets supply guardrails. Analytics support decision-making. Because those four processes run on a single AI-native legal platform, approved accruals match previously reviewed invoices, and the entire team has full visibility and context into the matter.
Where to start
Process enhancement should be iterative. Teams that bypass foundational steps — moving directly from collecting data via email to automated forecasting — risk exacerbating existing issues.
Find your current stage
Three stages describe most in-house spend management functions:
- Manual: Accruals are gathered at the end of the period by email, budgets are applied inconsistently, reporting is built on invoices, and surprises are often found during close.
- Standardized: A common calendar and templates are in place, there are defined owners, matter budgets are generally required, there is a review of regular budget-to-actual, but the team is still dependent on spreadsheets.
- Connected: Accrual requests and reminders run automatically, billing and matter data sit together, variance thresholds trigger review, and forecasting informs decisions.
Sequence the first quarter
Finish one stage before starting the next. A quarter is enough time to move one full step forward when the work is scoped strategically.
Follow these steps as an initial guide, then iterate as needed:
- Diagnose: Document the current accrual workflow, inventory data sources, review the largest historical variances, and select baseline metrics.
- Standardize: Publish the accrual calendar, align with Finance on materiality and escalation rules, build a budget template, and formalize outside counsel expectations.
- Connect: Reduce email handoffs, set threshold alerts, integrate matter and spend data, and move to exception-based review.
Targets should scale with department size, matter volume, and budget. ACC makes the same point about its maturity model, which is a benchmarking reference rather than a universal standard.
If a decision on moving to a new legal platform sits at the end of this sequence, the criteria for evaluating ELM vendors should reflect the stage you are moving into, not the one you are leaving, so you ensure your team is always moving forward.
From reporting spend to managing it
Transitioning from tracking past departmental expenses to forecasting future spending is a crucial shift. This moves the focus from reactive historical reporting to proactive forward-looking visibility. Unforeseen budget variances are converted into managed exceptions, and manual spreadsheet reconciliations are replaced with governed data backed by a clear audit trail.
For legal leadership, the payoff is practical: it becomes possible to explain what drove a variance, flag emerging cost risks while there is still time to act, and support business planning with numbers Finance already trusts.
Request a demo to see how Litify connects matters, budgets, billing, and spend visibility in one platform.
FAQs
What is a legal accrual?
A legal accrual is the estimated value of legal work performed during a reporting period but not yet invoiced. It records the expense in the period the work happened rather than the period the bill arrives, keeping monthly and quarterly financials aligned with actual activity.
How is a legal accrual different from a matter budget?
An accrual measures unbilled work that has already been performed. A matter budget estimates the total expected cost of the matter from start to finish. The accrual is a point-in-time figure that resets each period, while the budget is a running plan revised whenever scope changes.
How often should legal accruals be collected?
Collecting accruals monthly is standard and aligned with the corporate close calendar, with added rigor at quarter-end and year-end. Departments that only collect quarterly tend to see larger variances, because firms reconstruct three months of activity from memory rather than reporting on recent work.
How do you improve accrual accuracy from outside counsel?
Standardize the submission format, publish a fixed calendar, and compare each estimate to the eventual invoice. Then share the results with the firm. Most accuracy problems come from unclear expectations or late requests rather than unwillingness, and firms that see their own variance history usually correct it without being asked twice.
What metrics show that legal spend management is improving?
Accrual accuracy against eventual invoices, on-time submission rate before the cutoff, budget variance between actual and accrued spend and the approved budget, and forecast accuracy against final matter cost. Improvement shows up as tighter variance and fewer matters missing from the current forecast.
How can legal departments improve accrual accuracy and financial forecasting?
Accuracy improves when three conditions hold at once: the calendar is fixed and known to every firm, the required fields are identical for every submission, and estimates are reviewed against invoices, making patterns visible. Forecasting improves on that foundation because a forecast to complete is only as reliable as the accrual and budget data feeding it.
What are the best dashboards for monitoring legal spend, budgets, and accruals?
The most useful reports and dashboards answer management questions rather than list transactions. A practical set of dashboards covers matters that are predicted to exceed budget, spend growth by firm and business unit, accrual submission status against the current cutoff, and budget consumption against thresholds. Dashboards tied to matter records are better than standalone finance reports because the person reviewing a variance can see what the matter is without leaving the screen.
Additional sources
Association of Corporate Counsel (ACC), Building a Budget | ACC, External Resources Management | SEC Staff Accounting Bulletins